TL;DR
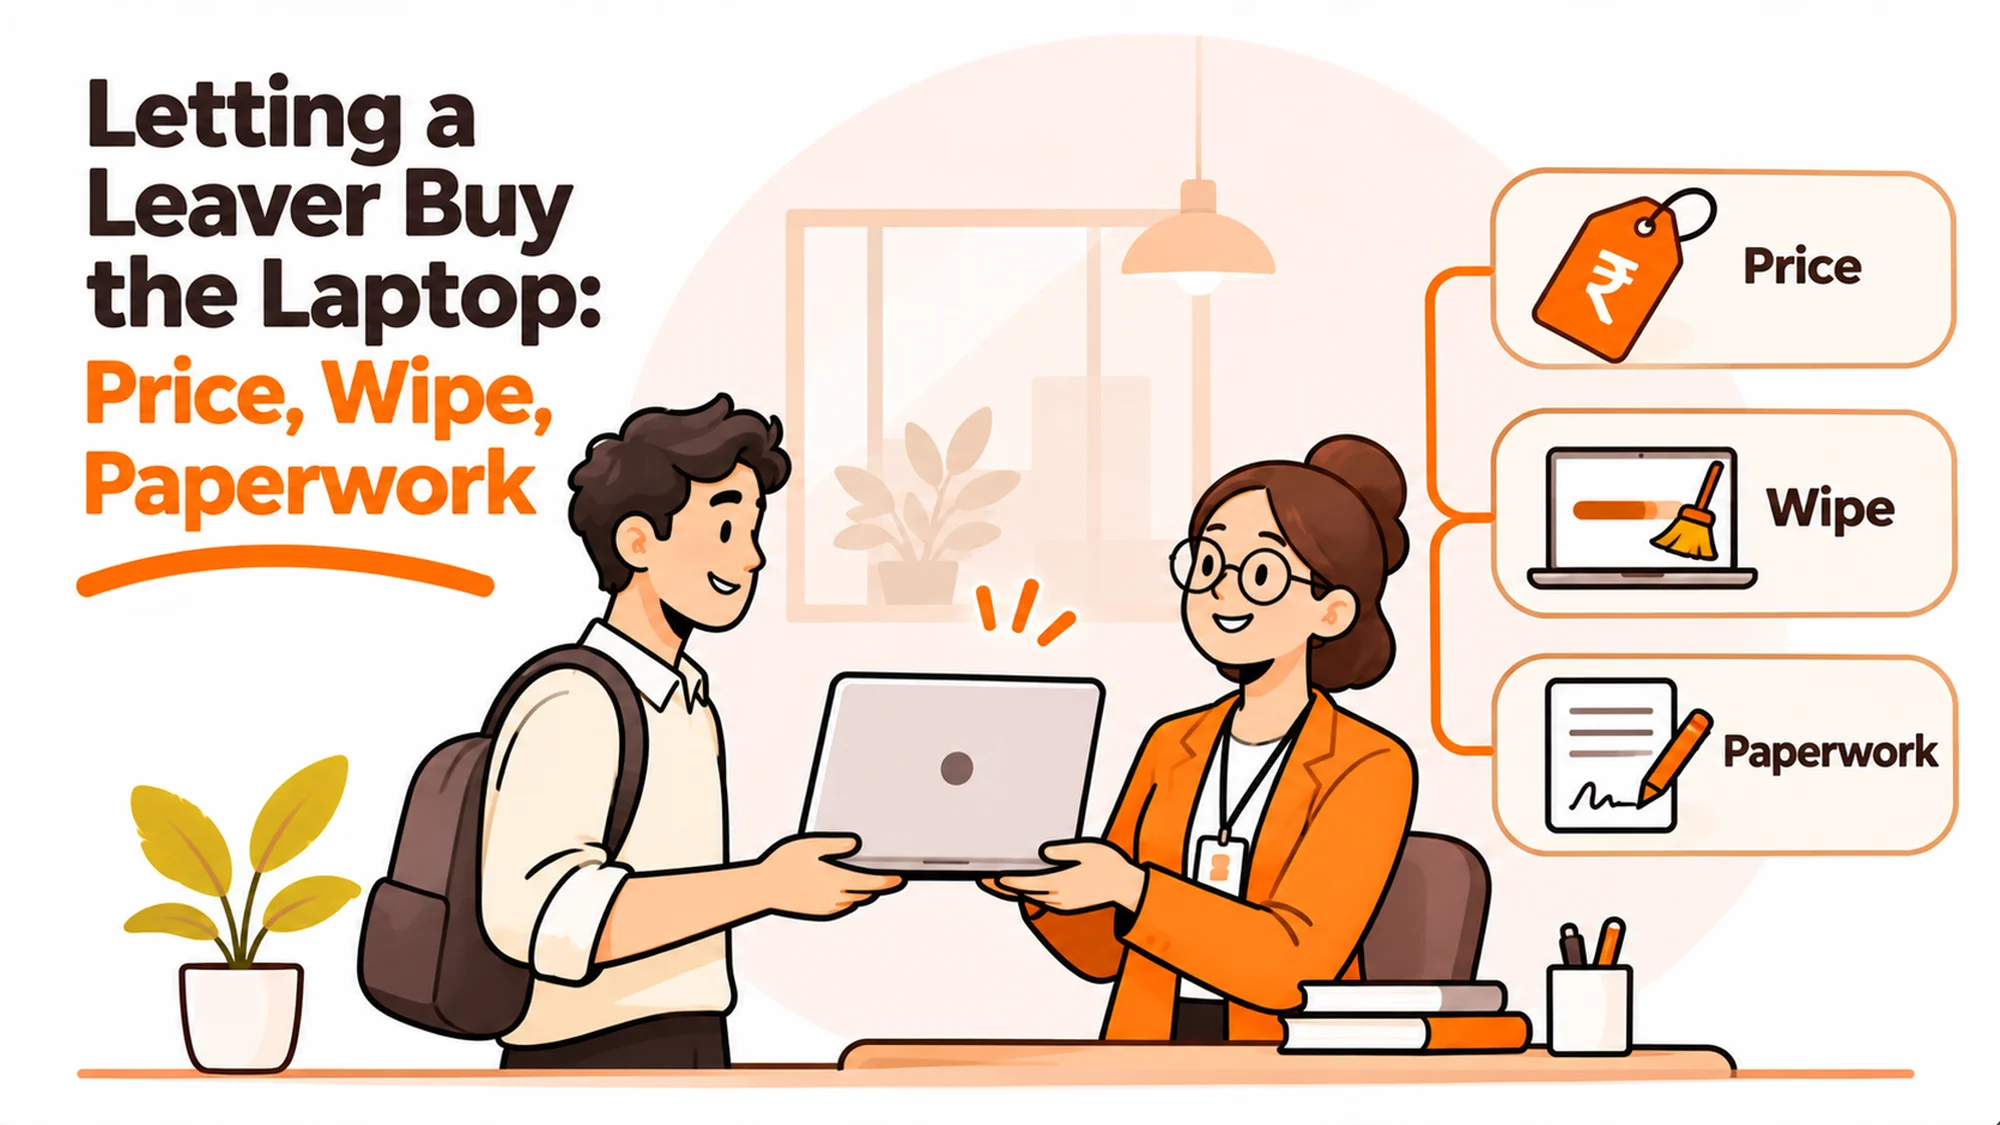
Letting somebody buy their laptop on the way out is an underused option. It removes a shipment, it is often popular, and it turns a depreciated asset into cash. A leaver laptop purchase also creates three obligations that teams routinely miss: pricing it defensibly, wiping it properly before it leaves your control, and recording it so it does not become an audit gap.
- It removes a shipment and a retrieval risk at once.
- Price from market value, not book value or purchase price.
- A discount below market value can be a taxable benefit.
- Wipe and rebuild before handover, not after.
- Remove it from the asset register with a sale record.
- Never offer it where the device held regulated data you cannot clear.
Why it is worth offering
There are four arguments for a leaver laptop purchase, and the first pays for the rest.
The device is already where it needs to be. No collection, no courier, no transit risk, no chasing. The most expensive part of offboarding disappears.
Best tools for Device Management
The money is better than scrap. A three year old laptop sold to its user typically beats what a processor pays for it.
People want it. They are used to the machine and it is configured how they like it.
It is the greener outcome. The device keeps working rather than entering a recycling stream.
Set against that, it only works where the data can be cleared with confidence and the paperwork is done. RemoAsset’s laptop retrieval service for remote teams is still the right route for everything else, and most companies will run both.
Where it does not apply
Devices holding regulated or customer data that you cannot verify as cleared, machines still under a lease you do not own outright, and anything within a warranty or support contract you intend to keep using.
Pricing it so it survives scrutiny
Three numbers get confused here and only one of them is the right basis.
Purchase price. Irrelevant. The device is years old.
Book value. What finance has it at after depreciation. Useful internally, not a market price. equipment depreciation and what finance needs covers how that figure is built, and IRS Publication 946 on depreciating property is the underlying reference in the United States.
Market value. What the same model, age and condition sells for in the secondary market today. This is the correct basis.
Get it from a real source: a refurbisher quote, a buyback quote, or current listings for the same configuration. Write down where the figure came from and the date.
| Basis | Use it for | Safe to sell at? |
|---|---|---|
| Purchase price | Nothing here | No, unfair |
| Net book value | Accounting entry | Only if near market |
| Market value | The sale price | Yes |
| A round number | Convenience | Only if evidenced |
A documented market figure protects both sides. An invented one creates the tax question in the next section.
The tax question nobody raises
Selling an asset to an employee below its market value can be treated as a benefit in many jurisdictions, with consequences for both the individual and the employer.
That is not a reason to avoid the arrangement. It is a reason to sell at a defensible price and keep the evidence.
the UK guidance on homeworking expenses and benefits covers related ground for UK employers and HM Revenue and Customs is the authority to check with. Elsewhere, ask your payroll provider, who will have seen the question before.
Two practical rules keep this simple. Sell at a documented market value rather than a nominal sum, and treat a deliberately generous price as a recognised benefit handled through payroll rather than as a quiet discount.
The construction to avoid
Gifting the laptop as a thank you with no value recorded. It is well meant and it is the version most likely to create a problem, because there is no price, no record and no evidence of what the device was worth.
If you want to be generous, do it with an agreed price and an explicit decision, not by omitting the paperwork.
Wipe before handover, not after
This is the step that gets skipped because the device never leaves the person’s possession, which makes it feel like nothing has changed.
Everything has changed. The moment the sale completes, a machine holding your company’s data belongs to somebody who no longer works for you.
The sequence that works: the person backs up anything personal, the device is wiped and rebuilt to a clean state using a method from NIST Special Publication 800-88 on media sanitization, the sale completes, and the machine is handed over clean.
Doing it remotely is straightforward with a management tool, which can wipe and reinstall without the device coming back. Where that is not available, the device has to come in, which removes much of the benefit and should be priced into the decision.
What to confirm in writing
- The device was wiped, with the date and method, against the serial.
- Management enrolment and any company software licences were removed.
- The buyer understands no company software or support transfers.
- Any recovery key is destroyed after the rebuild.
RemoAsset’s data wiping and offboarding service produces that record per serial, which is the artefact an auditor will want.
The record that closes it
Short, and it prevents the device becoming an unexplained gap later.
A one page sale note covering: serial, model, sale price, basis for that price with its source and date, confirmation of the wipe with method and date, the date of transfer, and a line stating the device is sold as seen with no warranty or support from the company.
Then update the asset register. Mark it sold with a date rather than deleting the row, so the history reads correctly at the next reconciliation. ISO 55001 on asset management is the framing, and how to calculate device total cost of ownership covers how the disposal value feeds the cost picture.
Finance needs the disposal entry too, which is usually straightforward once a price and a date exist.
The one sentence worth including
That the sale is voluntary on both sides. It avoids any suggestion that buying the laptop was a condition of leaving, which is the sort of thing that reads badly if the departure was contentious.
How and when to offer it
With a leaver laptop purchase, timing matters more than the offer itself.
Offer at notice, not on the last day. The person has time to decide, you have time to price it, and the alternative route can still be arranged if they decline.
Make it explicitly optional and make the default clear: if you do nothing, here is your return label and collection date. Nobody should feel they have to buy a laptop to leave cleanly.
Decide in advance which departures qualify. Most companies offer it regardless of circumstances for simplicity, and some exclude dismissals for cause. Either position is defensible; what causes trouble is deciding case by case.
Who should run it
Whoever already owns the offboarding checklist, with finance providing the price. If it sits with nobody, it becomes an occasional favour granted to people who think to ask, which is exactly the inconsistency to avoid. what belongs in an equipment loan agreement is where the underlying agreement usually lives.
What it does to the fleet
Two effects worth planning for, one good and one easy to miss.
The good one: devices leave the fleet without a storage or redeployment step, which reduces pressure on the spare pool and on wherever you keep returned kit. RemoAsset’s device storage and redeployment service absorbs the ones that do come back, and fewer of them means a smaller holding.
The one that catches people out: you lose the redeployment option. A device sold to a leaver is not available for the next joiner, so if your refresh plan assumed reuse, selling changes the purchasing forecast.
That matters most at small scale. If you hire ten people a year and sell every returned laptop, you buy ten machines a year instead of five. budgeting for equipment with uncertain headcount covers that planning problem.
The resolution is usually straightforward: offer the purchase on devices past the age where you would redeploy them anyway, and retain the newer ones. RemoAsset’s laptop procurement service is where the replacement side sits.
A reasonable default
Offer the purchase on anything older than your redeployment threshold, retrieve everything newer, and review the threshold annually against what machines actually cost.
[Two-CTA block: Case Studies | Talk to Expert]
Frequently asked questions
Is a leaver laptop purchase a good idea?
Often, for four reasons. The device is already where it needs to be, so there is no collection, courier, transit risk or chasing. The money usually beats what a processor would pay. People want the machine they are used to. And it keeps the device working rather than entering a recycling stream. It does not apply where the device held regulated data you cannot verify as cleared, or where it sits under a lease you do not own outright.
How should the price be set?
From market value, meaning what the same model, age and condition sells for in the secondary market today. Purchase price is irrelevant because the device is years old, and net book value is an accounting figure rather than a market one. Get the number from a real source such as a refurbisher quote, a buyback quote or current listings for the same configuration, and write down where it came from and on what date.
Are there tax consequences?
There can be, and they differ by jurisdiction. Selling an asset to an employee below its market value may be treated as a benefit, with consequences for both the individual and the employer. That is not a reason to avoid the arrangement, it is a reason to sell at a defensible price and keep the evidence. The construction most likely to cause a problem is gifting the laptop with no value recorded at all.
When should the device be wiped?
Before handover, which is the step most often skipped because the machine never leaves the person’s possession and so it feels as though nothing changed. The moment the sale completes, a device holding company data belongs to somebody who no longer works for you. Back up personal files, wipe and rebuild to a clean state using a recognised method, complete the sale, and hand over a clean machine with the wipe recorded against the serial.
What paperwork is needed?
A one page sale note is enough: serial, model, sale price, the basis for that price with its source and date, confirmation of the wipe with method and date, the transfer date, and a line stating the device is sold as seen with no warranty or company support. Then mark it sold with a date in the asset register rather than deleting the row, so the history still reads correctly at the next reconciliation.
When should the offer be made?
At notice rather than on the last day, so the person has time to decide and you have time to price it, with the alternative return route still arrangeable if they decline. Make it explicitly optional with a clear default: do nothing and here is your label and collection date. Decide in advance which departures qualify, because deciding case by case is what creates inconsistency and complaint.
Does selling devices affect our purchasing?
Yes, and it is easy to miss. A device sold to a leaver is not available for the next joiner, so if your refresh plan assumed redeployment, selling changes the buying forecast. At small scale this matters a lot: hire ten people a year and sell every returned laptop and you buy ten machines instead of five. The usual resolution is to offer the purchase only on devices past the age where you would have redeployed them.